

I sat down at a 15-person dinner last week at a restaurant downtown and my first thought before looking at the menu was who is going to be putting this on their credit card?1
It had me thinking more broadly about how we pay for things, or more accurately, how we pay for things through each other.
I have paid for hotels, flights, dinners, and tickets for groups of people more times than I can count. The highest amount I remember fronting was a $2,000 Airbnb for a bachelorette party, which I then spent the next few months hitting the “remind” button on Venmo requests and sending increasingly passive aggressive texts. One person paid me back in $50 installments that I had to manually track.
The idea of owing someone money is horrifying to me, maybe because I’ve never carried debt, or because of my social anxiety, or a rigorous adherence to social conventions. Which is perhaps why I find it genuinely baffling that there are people who just … don’t seem to care?
But this isn’t about a few flaky friends or bad Venmo etiquette. It’s about how the rising cost of maintaining a social life has turned friend groups into informal credit markets. We already live in an economy where everyone feels like they’re getting nickel-and-dimed by every company, product, and service they interact with. We do not expect to feel the same way about the people we love. But increasingly, we do.
The summer of financed fun
Having a social life has gotten dramatically more expensive over the past few years (aka funflation), but this summer in particular is testing everyone’s limits.
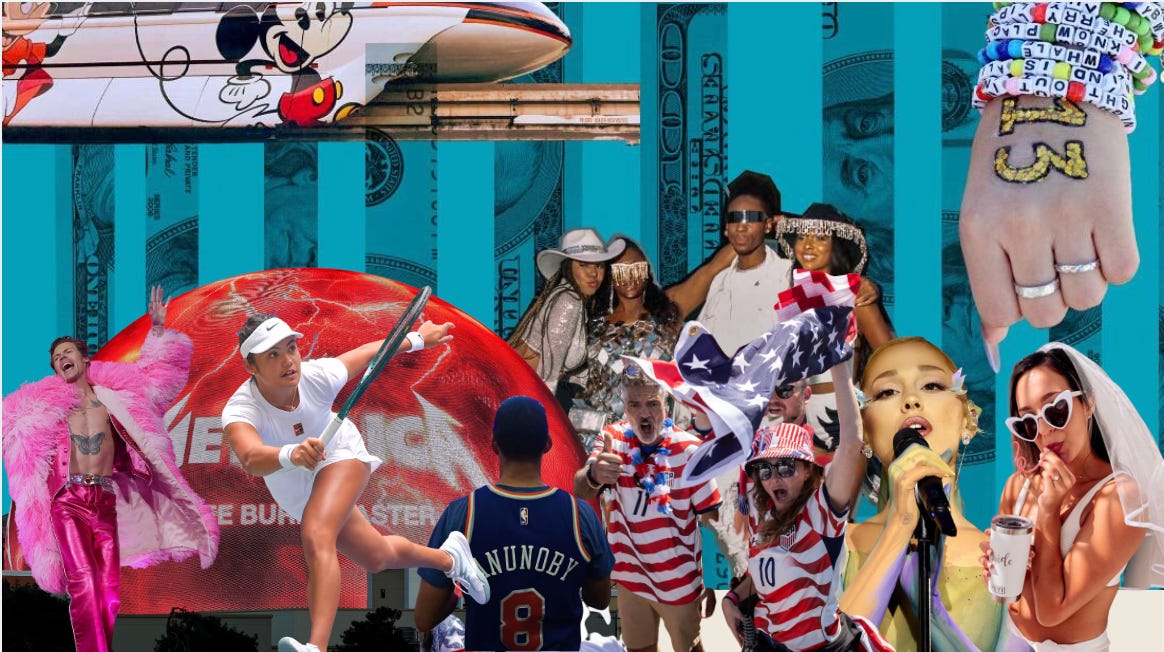
I’m personally watching it play out in real time in NYC. Average tickets to see the World Cup at MetLife Stadium are around $1,300, with finals tickets starting at $10,000. Ariana Grande tickets at Barclays are averaging $2,500. Harry Styles’ residency at Madison Square Garden ranges from $800 to $1,500. U.S. Open passes are averaging around $600 (something I’m especially sad about). Festival weekends, destination bachelorettes, weddings, movies, flights, hotels — things that used to be a normal part of summer fun now require the kind of financial planning that used to be reserved for, like, buying a car.
And Gen Z is still paying for all of it in part because they’re coming of age in a period marked by high rents, student debt, and income growth that hasn’t kept pace with the cost of living, and in part because everything feels like a once-in-a-lifetime event now.
The World Cup is being hosted in your city. It’s your favorite artist’s first tour in years. It’s your best friend’s wedding. It’s the group trip everyone has been talking about for months. There’s an urgency to all of it — a FOMO that’s partly real and partly manufactured by social media — so people spend money they don’t have because opting out feels worse than going into debt.
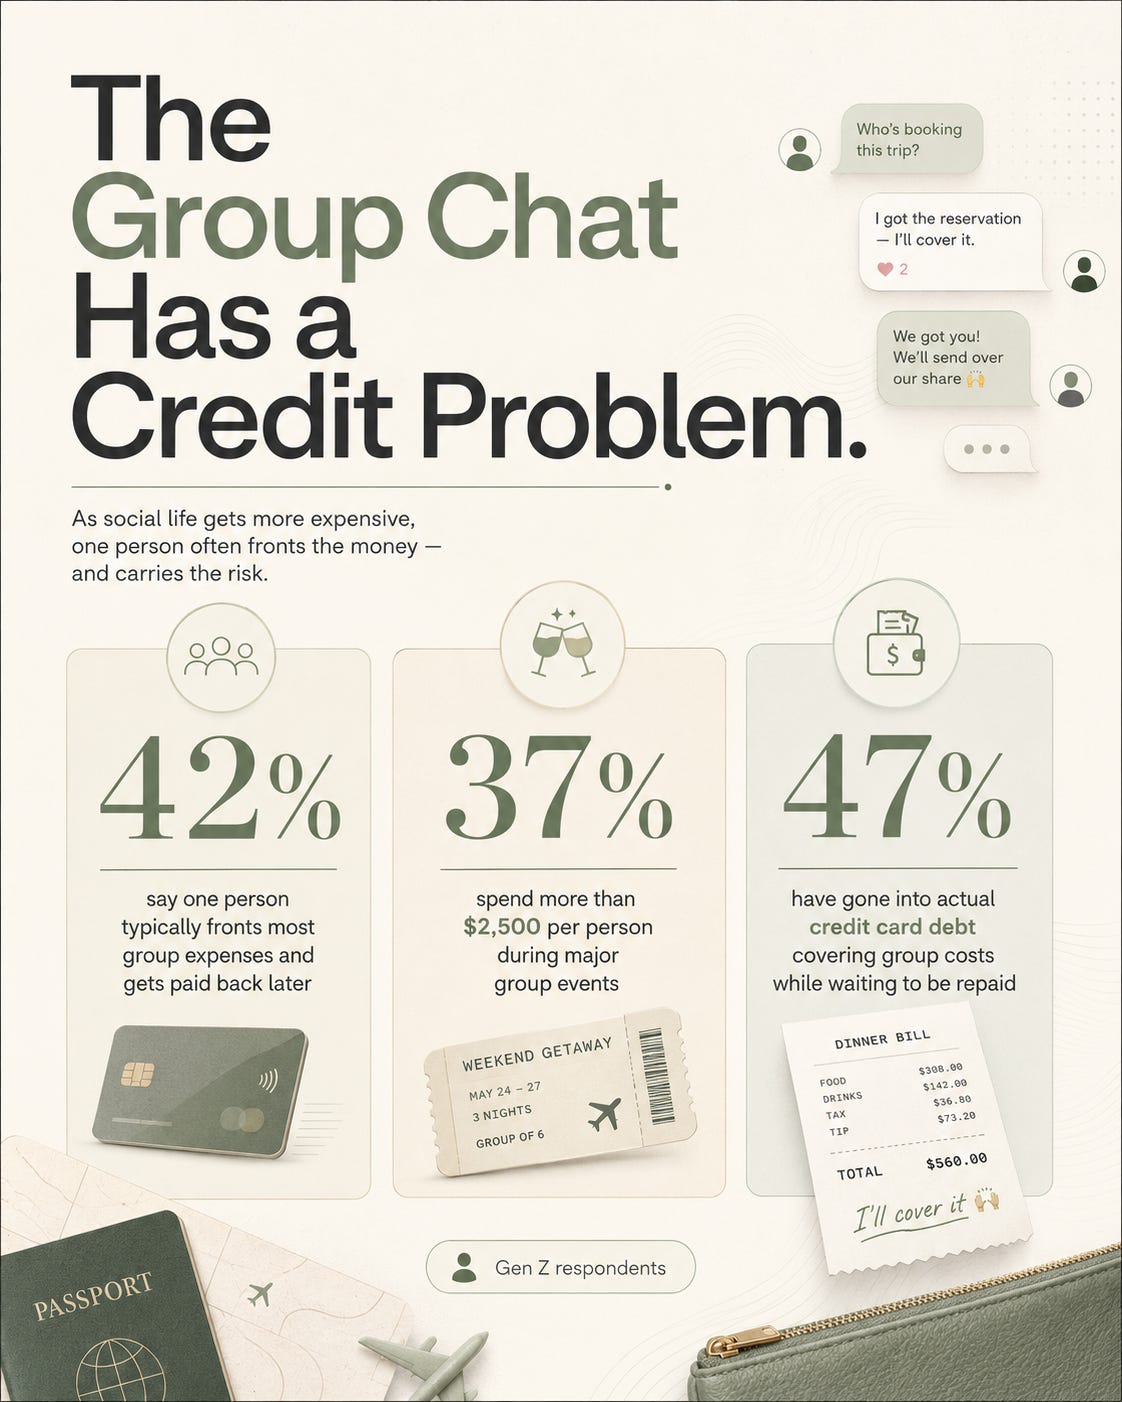
Many young people treat live events as social currency, something you post, share, and build identity around. 86% have admitted to overspending on live events. And increasingly, the way they’re financing these experiences is through each other.
Payment apps like Venmo position themselves as a convenient way to split costs (and they can be). But what’s the price of that convenience?
The friend who fronts the bill is providing an unsecured, interest-free loan backed by nothing but the value of the friendship. These apps have essentially created a lending network, where one person supplies the liquidity, everyone else gets to consume now and pay later.
This may sound like a dramatic take. But in a culture where debt has become so normalized, owing someone money can start to feel like no big deal. Until it is.
“Sorry, just seeing this”
Friend-to-friend debt doesn’t feel like real debt, which is partially by design and partly because of the social norms that make it weird to ask for your own money back.
When you owe a credit card company money, you know it. You signed an agreement (which you probably skimmed, but regardless). There’s a balance, a due date, a minimum payment, interest that accrues, etc.
But when you owe a friend money, none of that infrastructure exists. The only record might be a Venmo request or a text. And because most friend-to-friend transactions are smaller than your monthly credit card payment or student loan installment, they carry less mental weight.
 Tiktok failed to load.
Enable 3rd party cookies or use another browser
Behavioral economists call this mental accounting, or the tendency to treat identical amounts of money differently depending on which psychological “bucket” they belong to. A $400 credit card bill often feels more urgent than $400 you owe your friend, because there are more tangible consequences for not paying on time.
And the fact that friendship is wrapped up in it makes everything fuzzier. Your friend (likely) isn’t going to charge you interest or send you to collections. The enforcement mechanism is the relationship itself, or the guilt, obligation, the fear of being seen as the friend who doesn’t pay. The “penalties” for not paying are entirely social, which makes them feel less real than other kinds of debt.
If you don’t pay your friend $200 back for that dinner, they probably aren’t going to come repo your couch. But they might stop inviting you out.
The money we borrow from our friends is almost never for something emotionally neutral. It’s for a birthday trip, a wedding, a concert your whole friend group is going to. Opting out of going (and paying) can feel like opting out of belonging. The social cost of not participating is often high enough that people spend money they don’t have just to show up. And then they can’t pay their friend back, which starts a whole different kind of social cost.
Meet the bank of the friend group
I’ve written before about how money makes friendships weird: how financial dynamics bring status, fairness, and entitlement into relationships that are typically supposed to be about trust and affection. Group expenses take all of those dynamics and put them on steroids.
When someone fronts the money, they become the group’s unofficial lender, whether they signed up for it or not. They take on the financial risk, the administrative work of tracking who owes what, and the uncomfortable job of chasing people down for repayment. And in some cases, they get punished for it — viewed as demanding or uptight for asking to be repaid for money they didn’t intend to loan out in the first place.
The person who owes money is often dealing with their own discomfort. They may feel ashamed, or defensive, or like their friend is keeping tabs on them. It creates an uneven power dynamic inside the friendship that neither person asked for and that neither person really knows how to talk about. There’s not really a script for “hey, I love you, but you’re making me feel like a collections agent.”
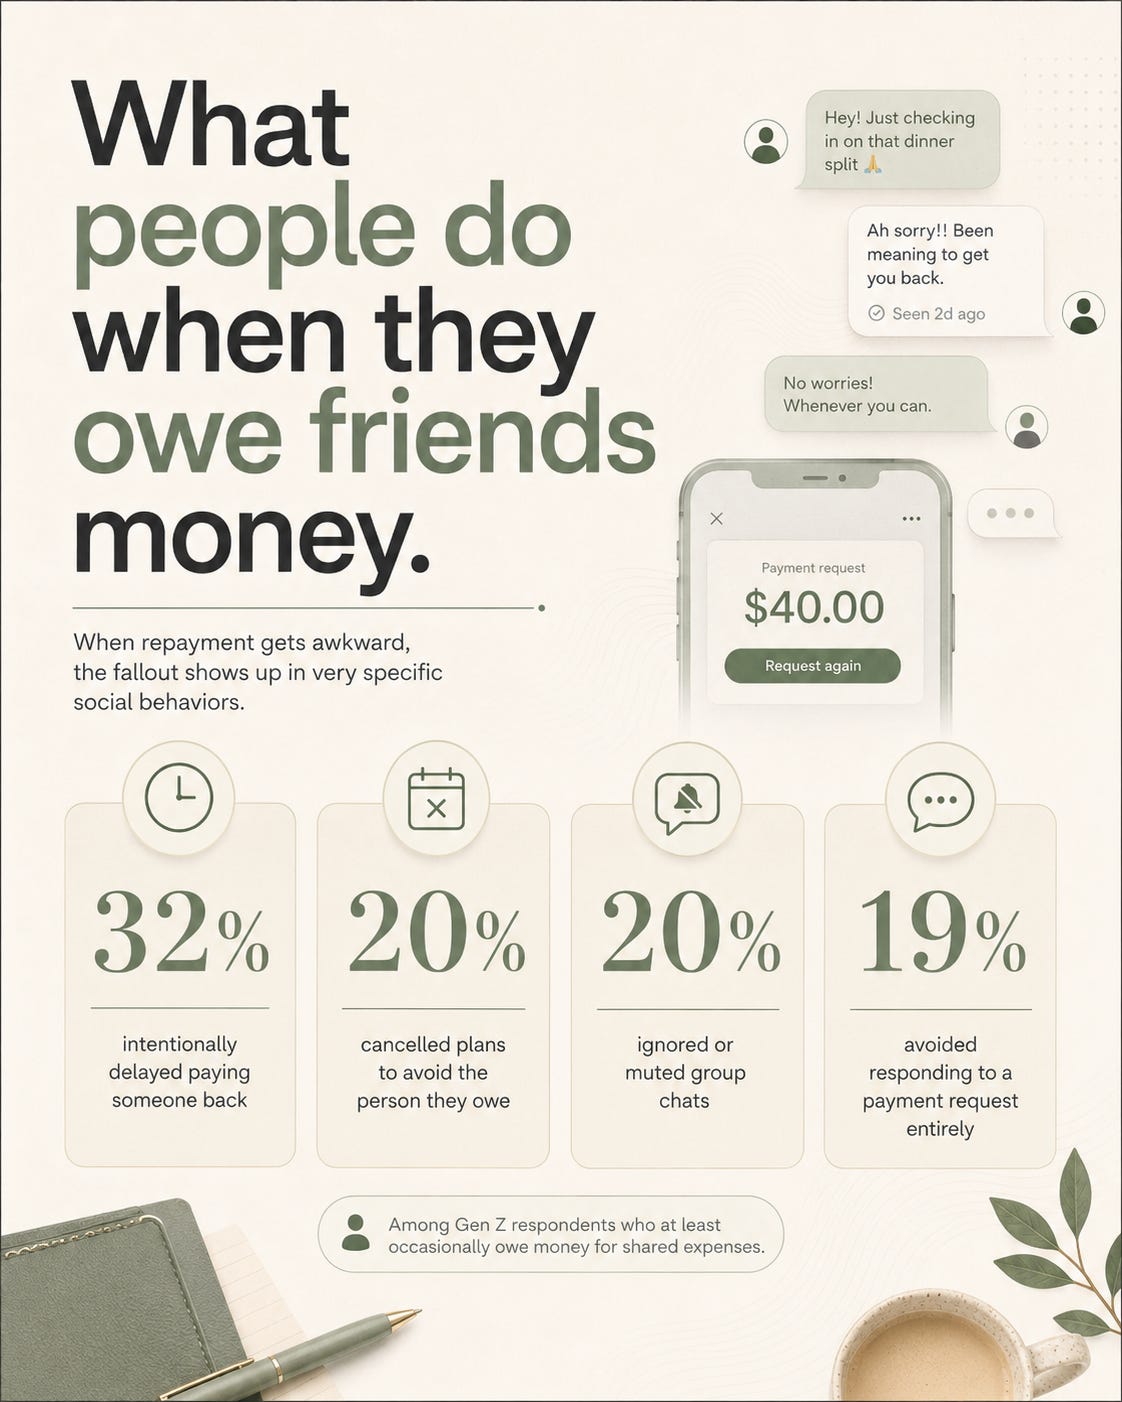
Money avoidance is a super common behavior, and it plays out here. Someone can’t afford to pay back right away. They feel embarrassed about it. The embarrassment makes them avoid the request. The person waiting for the money interprets the silence as disrespect. The borrower feels even more ashamed and pulls away further. You can see how one transaction can quickly spiral into a larger relationship rift.
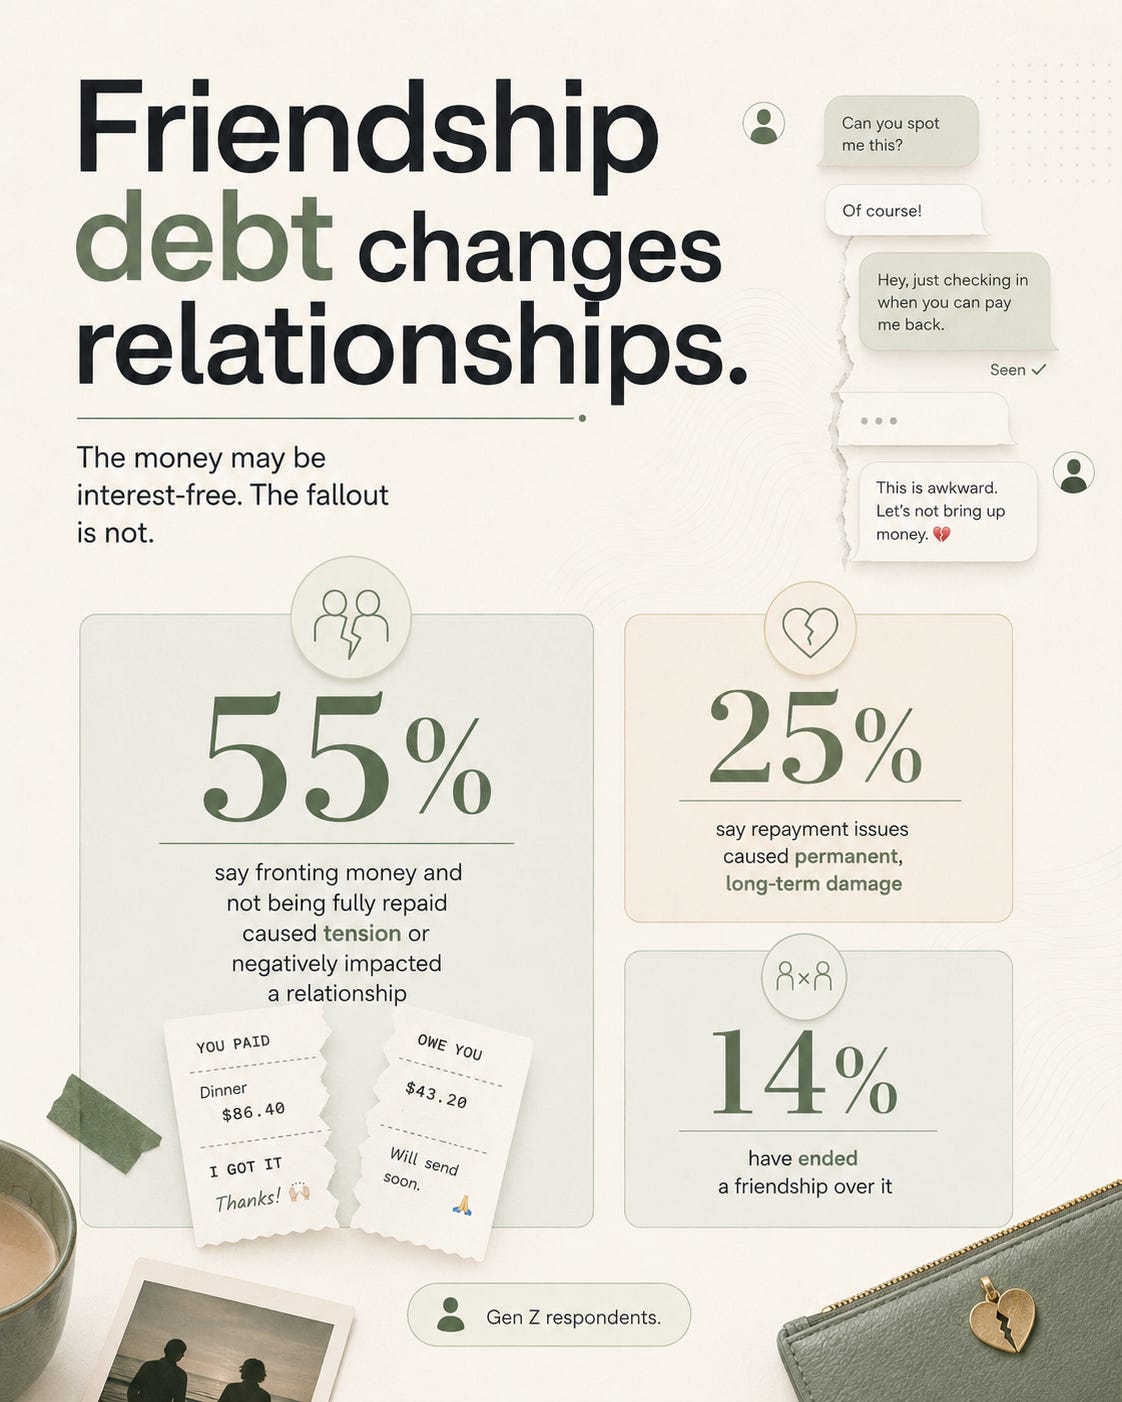
Once you get burned, it’s hard to feel generous again. 35% of Gen Z say they’ve chosen not to front money for group expenses because of past payment issues. Which means they may be opting out of the experiences altogether, because nobody wants to be the bank anymore.
I have friends who I would not lend money to under basically any circumstance, because I know from experience that getting paid back will be a months-long ordeal. And that sucks, because it changes the friendship, introducing a calculation into a relationship that’s supposed to be free of calculations.
The low-trust group chat
We already exist in an economy where people constantly feel like they’re being taken advantage of. Corporations use surveillance pricing to charge different people different amounts for the same product. Dynamic pricing means the cost of a concert ticket or an Uber changes depending on how badly you want it. Loyalty programs get worse every year. Every company seems to be searching for one more way to extract value from the transaction: a new fee, a smaller portion, a subscription that’s harder to cancel.
We can tolerate a certain amount of financial bullshit from Ticketmaster because we already believe Ticketmaster is trying to screw us. We do not expect to feel the same way about our friends.
But when social participation increasingly requires consumption, relationships start to feel more transactional. You start keeping score, noticing who always offers to pay and who always waits. You start calculating whether this friendship is worth the back and forth of someone owing you money.
Money has always been a part of friendships, but it’s become more overt: more tracked, more visible, and therefore more loaded. Partly because of the economy, where most people feel financially precarious enough that every dollar carries more weight. And partly how current technology has made every transaction logged and timestamped and visible.
When friendships become transactional, they weaken. And we genuinely need our friendships more than ever. Your friends are one of the most important buffers against loneliness and isolation (which are bad for us mentally and emotionally but also financially!). So it’s even more concerning that certain financial dynamics can actively erode the trust that holds those friendships together.
What’s the point of having friends?
Some lost money is just the cost of having friends. If you’re going to have real, close friendships with people, a certain amount of financial imperfection is going to come with the territory, and trying to eliminate it will make you the kind of person nobody wants to go to dinner with. But not everyone sees it that way.
But it’s harder to embrace a certain level of generosity when everything has gotten more expensive and most people’s financial margins have gotten smaller.
But the answer isn’t to stop being generous or to start Venmo-requesting your friends for $4 coffees. I think it’s to be more honest, sooner, about what you can and can’t afford — and to treat the moment you put your card down for a group as what it actually is: a loan. I wrote about this in an earlier essay, how the best thing you can do for your friendships is be direct about money, even when it’s awkward, because the alternative is resentment that builds silently until the friendship is permanently damaged.
Talk about the timeline for repayment. Be honest about your budget. Pay people back promptly and without being chased. And if you’re the one fronting money, it’s okay to set terms: “I need everyone to Venmo me by Friday,” for example.
The experiences we have (the trips, the concerts, the weddings) are supposed to be the best parts of life. It would be nice if we could figure out the money part without letting it ruin them.
Maybe I’m just extremely not normal but also I write about money for a living, so sue me. Also don’t worry, I didn’t involve anyone else in this semi-antisocial line of thinking.
"Festival weekends, destination bachelorettes, weddings, movies, flights, hotels — things that used to be a normal part of summer fun"
Most of these (excepting weddings and movies) were never a normal part of summer fun for anyone but the upper middle class. They still are not.
I am not really concerned about the costs of luxuries. Let destination bachelorettes and big-name concerts be expensive -- they are a luxury most Americans cannot afford and that's fine.
I am concerned about people who struggle to pay for necessities and a few basic "luxuries" like being able to send their children to a public swimming pool for an afternoon or being able to get ice creams after dinner once a week. When things like that are out of reach for millions of people, that's when we have a problem. And we DO have this problem, right now.
The real problem this essay is about is income inequality within a group of friends! If you are poor and have rich friends, either you will go into debt to keep up with them, they'll pay for you because they genuinely want you to share in the fun and know you cannot afford it or they will refrain from doing expensive things when with you and will choose cheaper activities. Or you will stop being friends.
I'm Germany, people are used to splitting bills and it's a non spoken norm that the waitress will charge every person separately. You just need to say what you ate or drank and tip on top. There are no big group expenses to cover. And if you say I got this it's because you are inviting the other person. Wouldn't be a matter of adopting something like that?