

People really hate the economy right now.
The University of Michigan’s consumer sentiment index dropped to the lowest reading in the survey’s 74-year history. Lower than 2008. Lower than the stagflation of the 1970s. Lower than any month of angry inflation discourse during the Biden presidency.
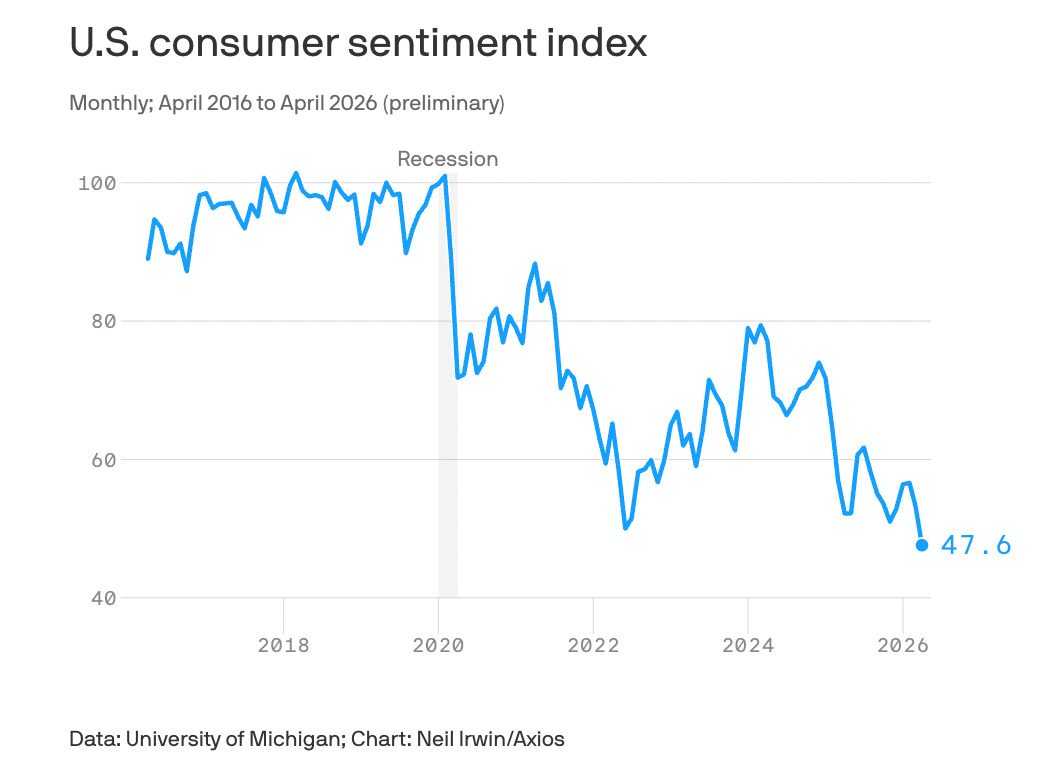
I don’t want to dwell on the fact that the headline numbers are still somewhat solid, because at this point that’s not a paradox — it’s the predictable surface read of a K-shaped economy where the top of the income distribution is doing better than ever and pulling the headline averages up with them.
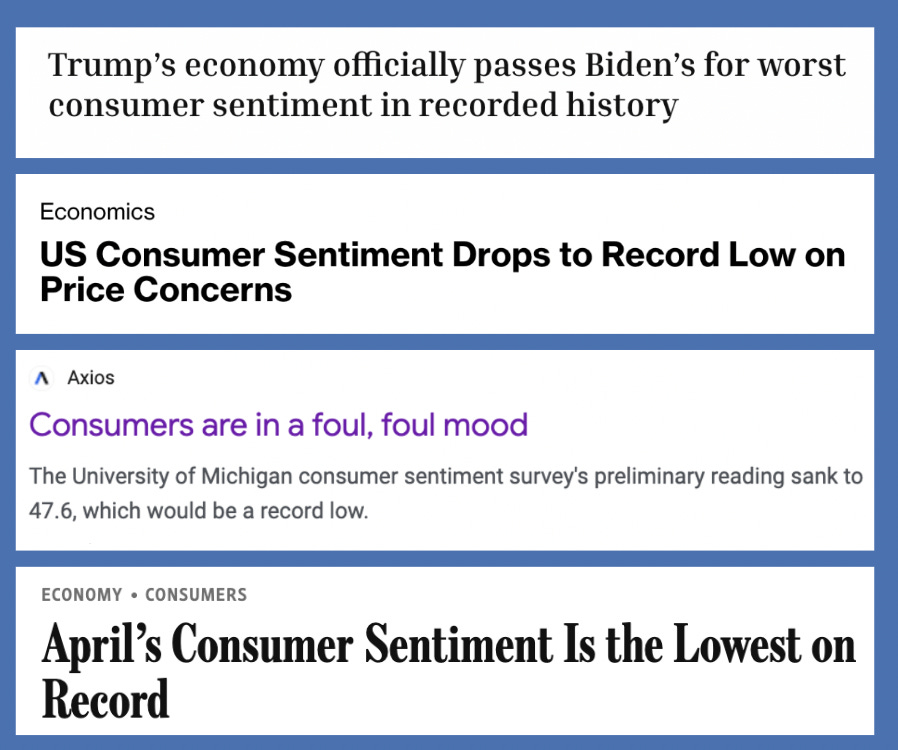
The more interesting question (to me) is what sustained economic misery actually does to a population.
Derek Thompson wrote a piece last week that takes the question seriously. He calls this decade the Tragic Twenties, and he walks through six years of unhappiness data to argue that the misery is real, structural, and not going anywhere:
“America’s resilient economy is a fact, while Americans’ sad-sack survey results are mere irrational feelings… But a feeling is an important kind of fact. Feelings don’t just shape consumer behavior. They shape political attitudes; and attitudes influence voting; and voting determines policies; and policies shape the economy.”
He’s right, but what happens next, once those feelings hit your wallet? Because chronic, generalized, six-years-and-counting economic misery produces specific consumer behaviors, specific cultural patterns, specific shifts in how an entire population relates to its own money.
What does it look like, psychologically, to spend money in this economy? What does this misery do to how we think about debt, status, the future, and ourselves?
Behavior one: reality distortion
When the information environment breaks, you can’t find yourself.
Daniel Kahneman’s prospect theory tells us a useful, simple thing: people don’t evaluate prices in absolute terms. They evaluate them against an internal reference point — a mental anchor for what something should cost, set whenever they first started paying attention.
When prices stay reasonably stable, this works fine. But what happens when prices move three, four times faster than they’re supposed to? The reference point breaks.
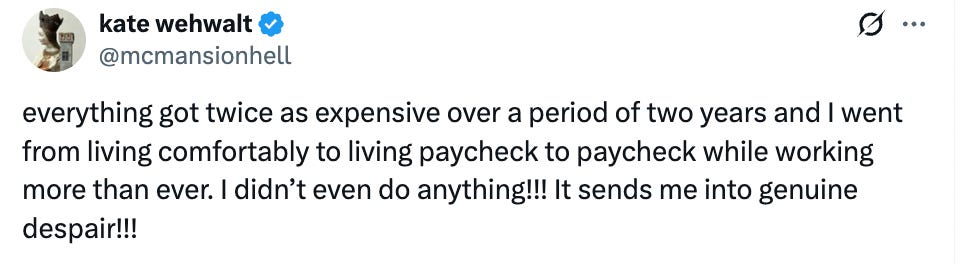
Cumulative inflation since 2020 has compressed roughly 13 years of normal price increases into 5. People remember $3 gas. $1,500 rent. $5 cartons of eggs. $14 entrees. And every single transaction now happens against those phantom prices, which the brain refuses to update because the brain didn’t agree to any of this.
It isn’t just inflation, though. It’s the broader sense that the information you need to make good financial decisions has stopped being reliable.
In a stable economy, you can roughly locate yourself — you know what a “normal” salary, rent, or grocery bill looks like, and you can calibrate your decisions against that baseline. In a less-good economy, the signals get jammed. Prices move too fast, the information we see online becomes performative, and official statistics feel disconnected from lived experience. You lose the ability to answer basic questions: Am I doing okay? Am I behind? Is this normal?
 Tiktok failed to load.
Enable 3rd party cookies or use another browser
These are some behaviors that emerge from this belief:
Reference-point grief — you’re basically experiencing sticker shock every single day, which is not only stressful but annoying.
Money dysmorphia — feeling broke and anxious at any income level because social media has hijacked your sense of where you actually stand (aka positional precarity)
Algorithmic paranoia — low-grade distrust of every transaction because dynamic pricing has trained you to assume there’s a better deal happening for somebody else.
Comparison spiraling — without realizing it, you may be constantly trying to measure yourself up to other people based on what they have, how much it (looks like they) make and spend, etc.
Pre-emptive cynicism — dismissing financial advice reflexively because the implicit assumptions (stable wages, normal home prices, jobs that exist in three years) don’t match your current reality.
You can’t make good decisions when you can’t trust the signals. And the signals stopped being trustworthy a while ago.
Behavior two: control displacement
When you can’t control the big stuff, you over-control the small stuff.
There’s a body of research from the behavioral economist Sendhil Mullainathan and the psychologist Eldar Shafir — they wrote a book called Scarcity in 2013 — that documents what financial precarity actually does to cognition. They found the experience of financial scarcity reduces effective IQ by roughly 13 points. It’s the equivalent of losing a full night of sleep.
The mechanism is what they call a bandwidth tax. When your brain is preoccupied with making ends meet, it has measurably less cognitive capacity for everything else. Financial precarity literally consumes executive function — leaving less bandwidth for the higher-leverage decisions (career moves, salary negotiation, comparing health insurance plans, long-term planning) that would actually change someone’s trajectory.
When the cognitive load gets high enough, financial agency redirects toward domains where they can still feel effective, like their routines, or bodies, or schedule. This includes:
Hyper-control or obsession over small expenses or your routine (I.e. the morning routine industrial complex)
The treat-yourself / restrict cycle — alternating between strict deprivation and compensatory splurging, mirroring patterns from disordered eating.
Anxious-avoidant financial optimization — a period of frantic budgeting, checking and/or financial optimization, followed by complete avoidance.
Outsourcing avoidance — paying more for convenience or avoiding the “adulting tax” because you’re so exhausted and burnt out from everything else.
Revenge saving — aggressively over-saving in response to anxiety, as a form of psychological control rather than a real plan. Extreme versions of FIRE (the financial-independence-retire-early movement) follow this.
All of this is very much rooted in exhaustion from trying to optimize against a system that won’t hold still.
Behavior three: defensive positioning
When falling behind has real consequences, spending becomes social insurance.
When you live in a tierfied economy — where every category has stratified into clearly visible levels of affluence, and where falling out of your tier (or class) comes with real social and material consequences.
Signaling that you’re still standing becomes existentially important — because falling out of your perceived class often means losing the network, opportunities, and relationships that might pull you back up. So spending stops being primarily about consumption and starts functioning as insurance against social demotion.
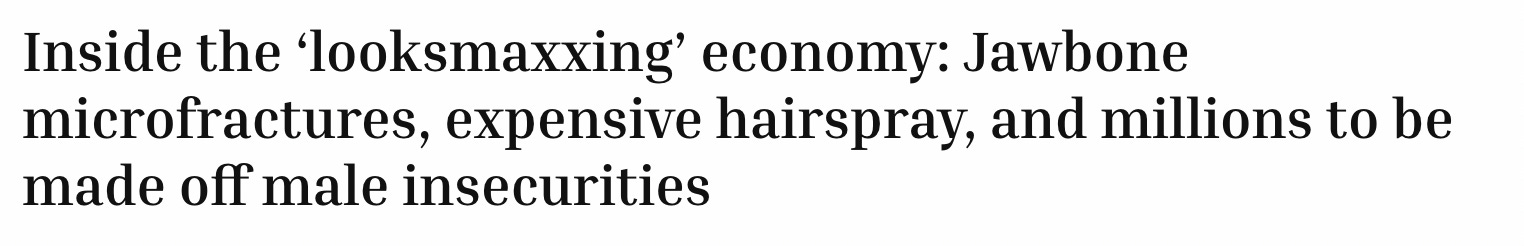
If everyone around you can see economic precarity (yours and theirs), the appearance of stability becomes a form of capital. This maps onto the idea of positional precarity, and consumer culture provides the vocabulary.
Brands, experiences, and aesthetics become legible markers that other people can read instantly. In a low-trust, high-anxiety economy, this legibility is enormously valuable — you can’t sit everyone down and explain your financial situation, but you can show up in the right sneakers, post from the vacation, or be seen at the right restaurant.
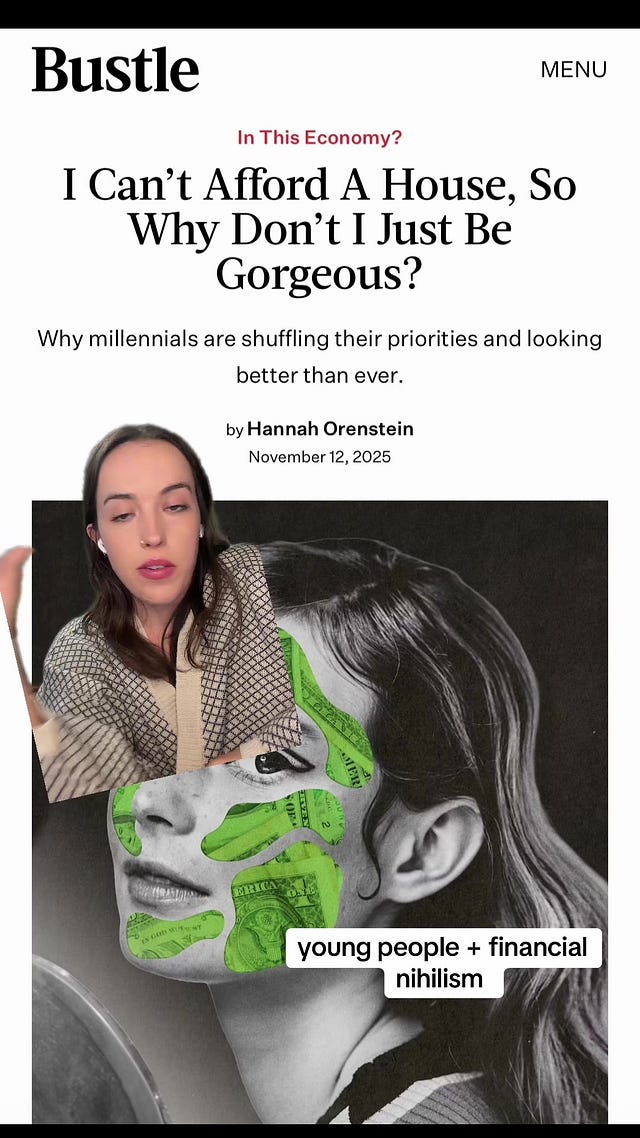
This could explain why the lipstick effect exists, why there’s an explosion of superfakes and designer dupes, why wedding costs continue to rise, why people are using buy now, pay later to go to Coachella, why members clubs are popping up everywhere, why little kids are spending hundreds on skincare, why plastic surgery is booming.
 Tiktok failed to load.
Enable 3rd party cookies or use another browser
It also shows up as:
Defensive lifestyle creep — spending more not to upgrade but to maintain the same standard of living you had three years ago.
Career immobility from benefits lock-in — staying in jobs you’d otherwise leave because health insurance and the 401(k) match feel too risky to give up.
Multi-job normalization — treating side hustles as a permanent feature of adult life
Pillar four: time horizon collapse
When the future stops feeling real, the present takes over.
When prices feel unstable and the future feels economically illegible, people rationally shorten their planning window. The behavioral economics term is hyperbolic discounting — the tendency to weight present rewards more heavily than future ones. In this context, I think it’s better understood as adaptive present-bias. When the future is uncertain and the present is painful, weighting the now is the rational move.
There’s a specific behavioral mechanism behind this called future self-continuity — the degree to which you feel connected to the version of you who will exist twenty or thirty years from now. People who score high on it save more, take on less debt, and exercise more. People who score low treat their future self like a stranger — and behave accordingly.
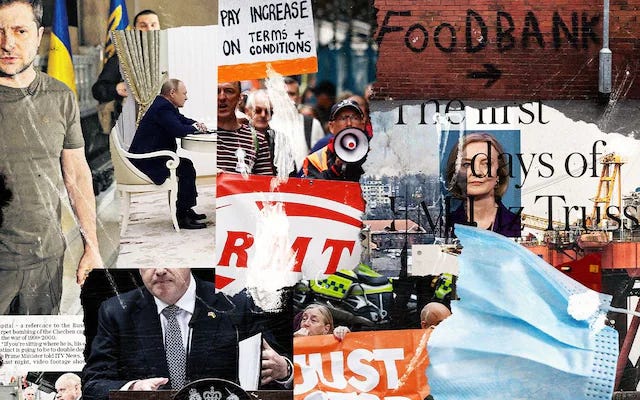
Now consider what six years of permacrisis news cycles do to that variable. When the headlines keep telling your nervous system that something terrible is always about to happen — pandemic, inflation, war, recession, AI, climate, election, war again — the future self stops feeling real. Why are you protecting her? She might not exist. Or her circumstances will be so different from yours that whatever you save now won’t matter anyway.
A Northwestern Mutual study released last month found that 80% of Gen Z believes high-risk speculative investments will outperform traditional ones. When researchers at the University of Chicago and Northwestern ran the lab version, they found that as someone’s perceived probability of homeownership falls, their willingness to take risky bets measurably rises.
This is how we end up doom spending, YOLO spending, or grifting online, or sports betting, or day trading, or investing in crypto, or using buy now, pay later. It also explains why many young people aren’t having kids, or getting married. Other specific behaviors include:
Doom spending — splurging on small luxuries because the big goals have stopped penciling out, so the math of delayed gratification has stopped making sense.
Lottery-brain investing — sports betting, options, crypto, meme stocks, prediction markets.
Quiet quitting on retirement planning — mentally writing off the idea that retirement will look anything like what was promised
Anticipatory milestone grief — mourning the house, the kids, the retirement you believe you won’t have, and making financial decisions from that place of pre-loss.
When the future doesn’t ostensibly exist to people, the present is now where all the meaning has to live. And once meaning gets concentrated in the present, the products engineered to provide it — the food, the clothes, the bets, the BNPL carts, the subscriptions — become hard to refuse.
How we talk about this matters
Most financial content treats these behaviors as individual psychology problems to be fixed with better habits. Stop spending on things you don’t need. Build a budget. Stop using BNPL. Don’t gamble on Kalshi. Save 20% of every paycheck. Develop discipline. Delay gratification.
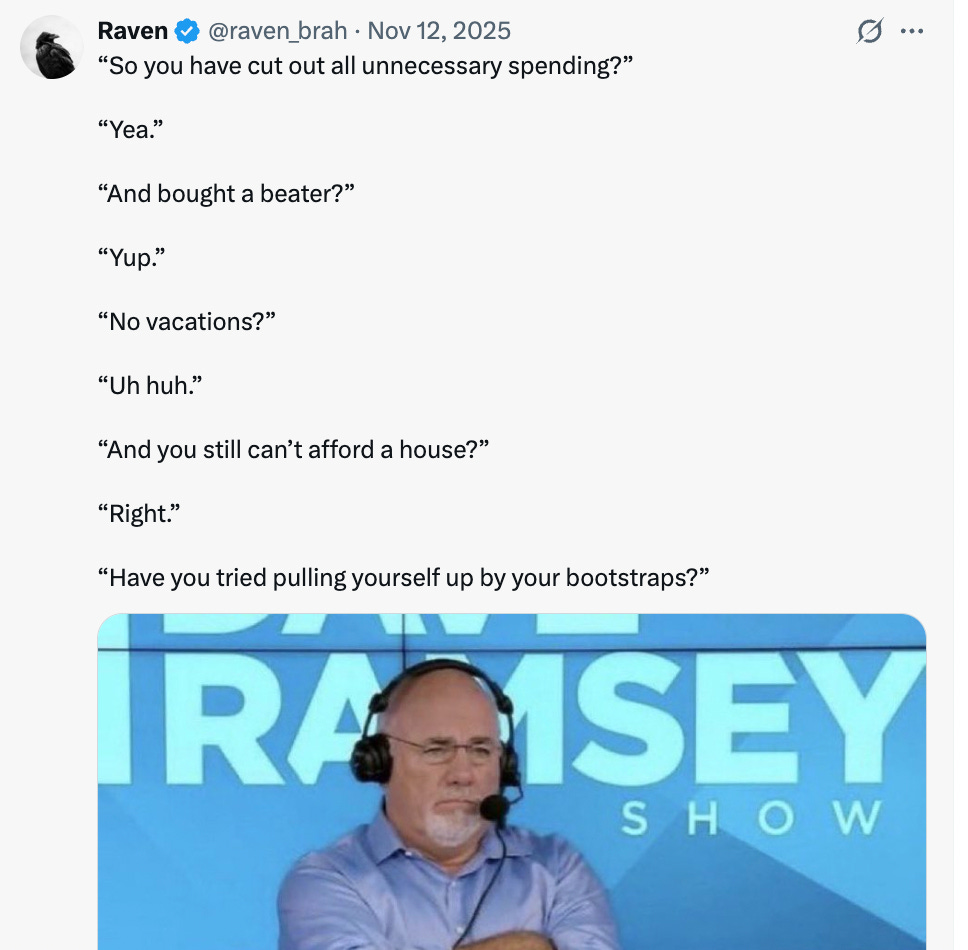
And like, sure, that’s all well and good, but it’s also deeply, structurally insufficient. And the way it’s delivered does real harm.
Because almost every behavior I’ve described in this piece is rational once you take the structural conditions seriously. If you frame all of that as a personal failure, you produce two outcomes, both bad.
You produce shame — which is one of the worst possible psychological states for sound financial decision-making, and which compounds the very behaviors it claims to fix. People spend more, hide more, gamble more, and disengage more when they feel ashamed of their financial life. Shame paralyzes, not motivates.
And you produce financial nihilism — the conclusion that since the system is rigged and the experts are wrong and the rules don’t work, the rational move is to opt out entirely. This is the version I find quite dangerous, because it has a kernel of truth wrapped around a prescription that does the user real harm.
The version of financial literacy I want — the version I’m trying to build with this newsletter — takes both halves seriously. The structural conditions, and the leverage you still have:
Here is how your brain is responding, sensibly, to a set of conditions that have shifted under you. Here is what those conditions are doing to your nervous system, your reference points, and your sense of what is reachable. And here is where you still have leverage anyway.
Financial nihilism is the mainstream position in today’s economy. So the most contrarian financial position you can take in 2026 is hope.
Rebecca Solnit has a line I think about constantly. She wrote a whole book on hope as a political category, and her central argument is that hope is not a feeling, it is the act of behaving as though the future is real, even when the present is screaming that it isn’t. Hope is an axe you use to break down a door.
The contrarian financial move right now is the boring one. Saving anyway. Imagining your future self anyway. Refusing to treat tomorrow as fictional, even though every product you encounter today is engineered to convince you it is. Knowing that the system was designed without you in mind, and refusing, regardless, to surrender the part of your life that is still yours to plan for.
It will not fix the entire economy. It will not lower your rent. It will not change inflation or how unaffordable things have gotten or how out of control things can feel.
But it will give you back a future self to plan for. And the act of planning — even a small, half-funded, badly executed plan — is itself a refusal of the story being sold to you, which is that there is no point.
That, in the end, is what hope actually is.
The other day I went to the mall for the first time in a long time and was shocked by how busy it was. I had a thought, like, “the recession and wealth gap indicator is the absurd amount of people at the mall right now,” but I didn’t know exactly how they were all correlated. This article squared that circle for me.
I learned a lot about my own habits in this piece and, while I never stopped saving, I certainly feel more disconnected from my future self than ever. Going to try hope from here on out. Thanks for the excellent breakdown and insight.
Great discussion. Intentional change theory (ICT) suggests that when you focus too hard on "negative emotional attractors - NEA," such as spreadsheets, numbers, finite things, you find yourself less likely to create sustained desired change. However, if you focus first and mostly on positive emotional attractors - PEA (vision, future self, hope, take walks outside, etc), you are more likely to create sustained desired change. ICT also includes identifying social identity groups, generating "what if" scenarios to uncover roadblocks, and more. This discussion touches on much of that and how it's affecting people on a day-to-day basis.